How to Manage Event Insurance Liability Risks: Complete Guide
Staging modern corporate conventions, multi-day congresses, music festivals, and trade exhibitions introduces complex legal exposures far beyond standard venue contracting. Organizers assembling thousands of participants in shared environments face an uncompromising imperative. They must navigate tort law, property damage, bodily injury claims, and intellectual property infringement. Left unaddressed, catastrophic accidents, structural rigging failures, weather disruptions, or cyber breaches trigger devastating liabilities. These incidents can dismantle an organization’s balance sheet entirely.
Achieving long-term legal protection and financial resilience demands looking beyond basic certificate-of-insurance collection or standard liability wrappers. This requires mastering commercial underwriting mechanics and negotiating explicit additional insured endorsements. Planners must eliminate restrictive exclusions and deploy sophisticated risk transfer protocols to shift legal exposure away from the organizing entity. This technical manual serves as an exhaustive guide for identifying, analyzing, and preventing exposure across global event markets. It provides the framework necessary to manage event insurance liability risks across diverse operational sectors.
Understanding “how to manage event insurance liability risks”
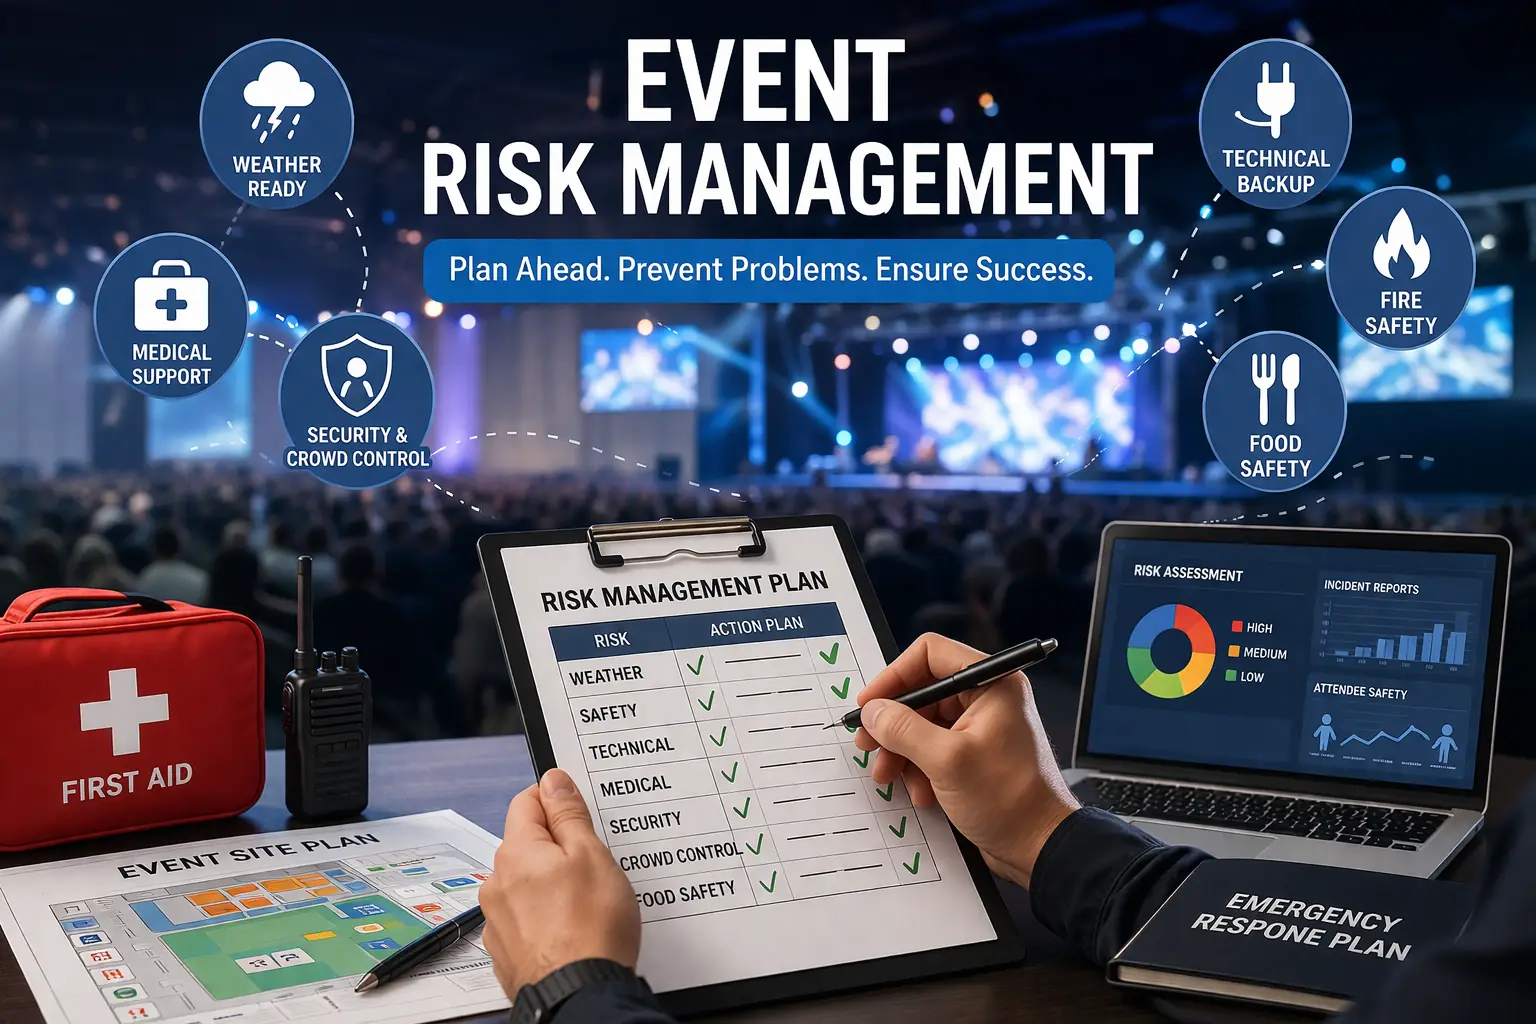
Analyzing professional strategies for managing event insurance liability risks requires separating standard retail consumer policies from enterprise-level master event underwriting agreements. The event risk management market is bifurcated into two distinct operational frameworks. The first framework comprises primary general liability policies, covering basic third-party bodily injury and property damage within designated venue footprints during operational hours. The second framework comprises comprehensive specialty lines. These include commercial umbrella excess liability, participant medical accident coverage, liquor liability, cyber security errors and omissions, and cancellation insurance, which insulate organizations from catastrophic secondary losses.
Corporate planning literature often assumes that securing a basic one-million-dollar general liability certificate satisfies all statutory and contractual exposure requirements. Accepting boilerplate policy limits without verifying underlying exclusions or waiver-of-subrogation clauses actually exposes organizations to millions in uncovered claims from subcontracted staging errors or unverified venue indemnities. Managing event insurance liability risks demands acute awareness of primary versus non-contributing wording, aggregate limits, completed operations extensions, and total cost of risk principles. Evaluating these insurance obligations through a multi-dimensional lens reveals a clear insight. Negotiating comprehensive additional insured endorsements for every contracted vendor and venue yields far greater legal protection than relying on standard policy defaults. Managing commercial event liability physically involves navigating adversarial insurance adjusters, complex venue indemnity covenants, and strict state tort statutes.
Deep Contextual Background: The Evolution of Commercial Event Underwriting and Tort Liability
The lineage of event insurance underwriting and commercial tort liability traces back to late-nineteenth-century industrial jurisprudence, public assembly venues, and common law negligence doctrines. As societies hosted mass gatherings, agricultural fairs, and theatrical exhibitions, courts established clear legal principles holding event promoters and property owners accountable for public safety. Insurance markets responded by developing specialized casualty lines to pool and distribute catastrophic injury risks across commercial underwriting syndicates.
Over the twentieth and twenty-first centuries, the commercial event landscape transformed rapidly due to extreme weather frequency, complex multi-vendor subcontracting chains, digital data vulnerabilities, and expanding litigation parameters. Insurers introduced rigid exclusionary riders regarding communicable diseases, cyberattacks, and structural rigging failures. This forced planners and producers to develop sophisticated risk engineering protocols. This structural evolution turned event insurance procurement into an analytical discipline focused on contract redlining, independent risk assessment, aggregate limit tracking, and proactive claims management.
Conceptual Frameworks and Mental Models
To evaluate the financial exposure, legal risk, and underwriting adequacy of any event portfolio, industry professionals rely on several core mental models:
-
The Total Cost of Risk (TCOR) Model: This model calculates the aggregate financial burden of insurance premium outlays, deductible reserves, uninsured losses, and risk management administrative expenses rather than focusing solely on upfront policy costs.
-
The Risk Transfer and Indemnity Matrix: This framework analyzes how contractual liabilities are shifted downstream from event organizers to venue operators, independent contractors, and caterers through explicit hold-harmless agreements.
-
The Severity-Frequency Risk Exposure Grid: This mental model categorizes potential event hazards based on the mathematical probability of occurrence relative to the catastrophic financial magnitude of potential resulting claims.
Key Categories or Variations
Analyzing these structural variations reveals a stark reality. Failing to secure comprehensive general liability limits alongside explicit additional insured endorsements represents the most legally hazardous error an event producer can commit. Neglecting these safeguards leaves organizations entirely exposed to third-party claims and financial ruin.
Detailed Real-World Scenarios and Decision Logic
Navigating Uninsured Subcontractor Injuries in a Convention Center
Injured parties file a multi-million-dollar lawsuit naming the event organizer, the venue, and the AV supplier. Sound decision logic requires contracts to mandate that all suppliers carry minimum two-million-dollar CGL policies. These policies must name the organizer as an additional insured on a primary and non-contributing basis, shifting defense and indemnity obligations entirely to the negligent vendor’s insurer. Failing to collect verified certificates of insurance before load-in forces the organizer’s balance sheet to absorb primary legal liability.
Managing Weather-Induced Event Cancellation Losses
Operational protocols require negotiating broad all-cause event cancellation policies. These policies must include adverse weather, civil commotion, and transportation strikes without restrictive localized geographic exclusions. Planners avoiding narrow exclusions protect non-refundable artist deposits and venue rental prepayments against sudden municipal shutdowns. Operational protocols require negotiating broad all-cause event cancellation policies. These policies must include adverse weather, civil commotion, and transportation strikes without restrictive localized geographic exclusions.
Planning, Cost, and Resource Dynamics
Managing event insurance liability risks requires a sophisticated financial architecture. Planners must understand direct versus indirect expenditures, opportunity costs, and variable underwriting deductibles.
Failing to audit vendor insurance certificates or negotiate comprehensive hold-harmless clauses creates severe opportunity costs. This negligence frequently results in catastrophic legal exposure, corporate insolvency, and permanent brand destruction. Consequently, financial allocation models must heavily weight rigorous insurance procurement, expert legal review, and proactive risk engineering during early planning phases.
Tools, Strategies, and Support Systems
-
Certificate of Insurance (COI) Tracking Platforms: Specialized software systems (such as Exigis or TrustLayer) automating the verification, compliance tracking, and expiration monitoring of vendor insurance policies.
-
Specialized Entertainment and Event Insurance Brokerages: Expert commercial insurance brokerages with deep access to global underwriting syndicates (such as Lloyd’s of London) specializing in complex event risks.
-
Comprehensive Venue and Vendor Indemnity Playbooks: Standardized legal addendums outlining mandatory hold-harmless agreements, waiver of subrogation terms, and minimum liability limits.
-
On-Site Safety and Risk Assessment Audits: Systematic inspection protocols identifying physical hazards, blocked fire exits, and structural rigging vulnerabilities before event opening.
-
Automated Claims Documentation and Incident Logs: Standardized digital reporting tools recording photographic evidence, witness statements, and timestamped incident details immediately upon occurrence.
-
Enterprise Risk Management (ERM) Software: Centralized platforms tracking organizational risk exposure, insurance portfolio expirations, and historical loss metrics across multi-event calendars.
Risk Landscape and Failure Modes
-
The Expired Certificate Trap: Collecting initial insurance certificates from contractors months before an event without verifying that policies remain active and uncancelled on load-in day.
-
Waiver of Subrogation Omissions: Failing to include explicit waiver of subrogation language in contracts, allowing insurance carriers to sue event organizers ssubrogatedthrough third-party vendors.
-
The Aggregate Limit Depletion Blunder: Contracting vendors whose total aggregate insurance limits have already been exhausted by previous claims earlier in the policy year, leaving the event unprotected.
Governance, Maintenance, and Long-Term Adaptation
Operating or utilizing large-scale event portfolios across enterprise organizations requires strict adherence to corporate governance standards, continuous audit regimes, and proactive risk management.
-
Layered Maintenance Checklist:
-
Master Insurance Portfolio Review: Comprehensive annual audit of corporate event insurance policies conducted with specialized brokers ninety days before policy renewals.
-
Vendor COI Compliance Verification: Mandatory collection and legal validation of all subcontractor and venue insurance certificates thirty days before event load-in.
-
On-Site Safety and Egress Inspection: Systematic physical walkthrough of event spaces conducted by designated safety officers twelve hours before public opening.
-
Post-Incident Review and Loss Run Analysis: Mandatory evaluation of any minor injuries or near-misses conducted within fourteen days of event conclusion to update future risk protocols.
-
-
Environmental Adaptation Triggers: Evolving global climate patterns, emerging cybersecurity threats, and changing statutory tort regulations require pre-established operational adjustments within event planning frameworks. Regional meteorological data often indicates escalating frequencies of severe convective storms. Planning teams must integrate mandatory weather-monitoring protocols and flexible venue evacuation riders into event insurance structures. This ensures organizers maintain financial protection against climate-driven disruptions without inflating baseline underwriting costs.
Measurement, Tracking, and Evaluation
-
Insurance Compliance Ratio (ICR): A quantitative metric tracking the percentage of contracted vendors and venues that successfully meet 100% of required insurance coverage minimums before load-in.
-
Total Cost of Risk per Attendee (TCOR-A): Tracking aggregate insurance premiums, deductibles, and risk management administrative expenses divided by total registered event participants.
-
Incident Frequency Rate (IFR): Quantifying the number of reported safety incidents, medical visits, or property damage claims per one thousand event attendees.
-
Claim Resolution Velocity (CRV): Measuring the average time elapsed between the formal reporting of an insurance claim and its final financial settlement by underwriting carriers.
Common Misconceptions and Oversimplifications
-
Signing a standard venue contract automatically provides full liability protection for the event organizer. Venue contracts typically favor the property owner through strict indemnification clauses that shift primary liability onto the event organizer.
-
Collecting a basic certificate of insurance guarantees that a contractor is fully covered. Certificates are informational summaries; planners must verify that specific endorsements—such as additional insured status and waiver of subrogation—are legally bound within the actual policy.
-
Event cancellation insurance covers all financial losses resulting from unexpected external disruptions. Basic cancellation policies exclude weather events, pandemics, and civil unrest unless specific, expensive riders are explicitly added.
-
General liability policies cover bodily injuries resulting from alcohol consumption at hosted bars. Standard policies frequently contain strict liquor liability exclusions, requiring dedicated separate riders for any event serving alcohol.
-
Small corporate meetings and internal workshops do not require formal event insurance or vendor COI tracking. Unforeseen slip-and-fall accidents or catering food poisoning incidents can occur at gatherings of any scale, making risk transfer essential.
-
Insurance brokers automatically include all necessary specialty coverages in standard event quotes. Planners must explicitly request specialized riders—such as cyber liability, participant medical, and non-appearance—tailored to their specific event activities.
-
Waiting until thirty days before an event is an effective time to begin insurance procurement. Complex specialty underwriting requires months of risk analysis and actuarial review, necessitating early engagement with brokerages.
-
If a subcontractor causes an accident, their insurance carrier will pay out without legal disputes. Insurers aggressively contest claims unless contracts contain precise, legally sound hold-harmless and primary-insurance wording.
Ethical, Practical, and Contextual Considerations
The procurement of commercial insurance and the systematic management of event legal liabilities introduce significant administrative responsibilities regarding public safety, participant welfare, and corporate governance. Managing enterprise event operations requires strict adherence to internal compliance policies, statutory safety codes, and transparent reporting practices. Planners and risk management professionals must ensure that insurance contracts and safety protocols comply with local health regulations, accessibility laws, and fair labor standards. This balances aggressive financial risk transfer with genuine participant protection and venue safety. Maintaining equitable access and robust safety standards for all attendees is a fundamental responsibility for ethical organizers, ensuring that physical environments accommodate individuals with diverse mobility needs without compromising emergency egress.
Conclusion
Mastering event insurance liability risks combines commercial underwriting intelligence, contract redlining, certificate verification, and specialty policy procurement. Effective risk management requires looking beyond basic general liability certificates. Planners must evaluate total cost of risk, additional insured endorsements, liquor liability riders, and cancellation protections. Navigating this landscape demands uncovering tort jurisprudence mechanics, underwriting exclusions, and risk transfer execution rather than relying on promotional summaries. As governance and event complexities evolve, this framework matures, offering disciplined planners a clear path toward financial protection and operational resilience.